
BAM Key Details:
- Redfin says U.S. housing costs could return to 2018 levels within five years if mortgage rates drop to 6% and home prices keep growing 2.1% a year.
- In 24 of the 46 metros analyzed, including Chicago and New York, costs could take 10+ years to return to normal.
How long until buying a home feels normal again? A new Redfin analysis says U.S. housing costs could get there within five or six years if mortgage rates come down or home prices stop climbing.
So, heavy emphasis on the “could.”
Plenty of buyers feel stuck right now. With rates near 7.5% and national home prices growing 2.1% a year, they’re trying to decide whether to buy at today’s costs or wait and risk paying more down the road.
Redfin ran scenarios for 46 of the country’s biggest metros, and the timelines can differ by a decade or more depending on where you live. Some West Coast and Texas markets are within a year or two of normal. Half the metros could take 10 years or longer.
Read on for the big takeaways and what they mean for your conversations right now.
How Redfin Defines “Normal”
Redfin measures housing costs with the mortgage-payment-to-income ratio. It’s the share of household income a buyer would need to spend on a monthly mortgage payment.
For this analysis, “normal” means the ratio has returned to where it was in August 2018. At the time, the national median mortgage-payment-to-income ratio was 30%, a common benchmark for affordability.
At the metro level, normal has a different meaning. It means a market’s home prices have returned to their 2018 level relative to local incomes. In pricey metros, a home can hit normal and still be out of reach for the typical household.
Redfin built its payment figures on a few assumptions:
- A 30-year mortgage with 20% down
- Payments include property tax and insurance, with insurance fixed at 0.5% a year
- Income growth based on Census data from 2015 to 2019
- 46 of the 50 most populous U.S. metros, the ones with enough data to include
Redfin says the scenarios are theoretical and shouldn’t be read as predictions. Each one is based on real trends in home prices and incomes, along with the range of rates economists expect over the next three to five years.
The National Timeline Depends on Rates and Prices
Redfin’s national scenarios show how much the timeline can move with modest changes in rates or prices.
Here’s how long it could take for U.S. housing costs to return to normal in each case:
- Within 5 years if rates drop to 6% and prices keep growing 2.1% a year
- Within 6 years, around 2032, if rates stay at 7.5% and price growth flattens
- By February 2029 if rates drop to 6% and price growth flattens
- 10 years or more if rates stay between 7% and 8% and prices keep growing 2.1% a year
Redfin calls the fastest and slowest scenarios unlikely, but says either one could happen. On the slow end, Redfin points out that prices would have a hard time growing 2.1% a year with rates that high unless home sales fell further.
West Coast and Texas Metros Are Closest to Normal
Falling home prices and strong income growth put a handful of West Coast and Texas metros ahead of the rest of the country.
San Jose, CA tops the list, and Redfin credits the Bay Area’s tech-driven economy for its strong income growth. At today’s 7.5% rates, San Jose’s costs could return to normal by October 2027. If rates fell to 6.5%, they could get there by November 2026.
Austin, TX comes in second, and its costs could return to normal by February 2028 at 7.5% rates. Prices there have dropped because of slow buyer demand and plenty of supply, which Redfin ties to pandemic-era overbuilding.
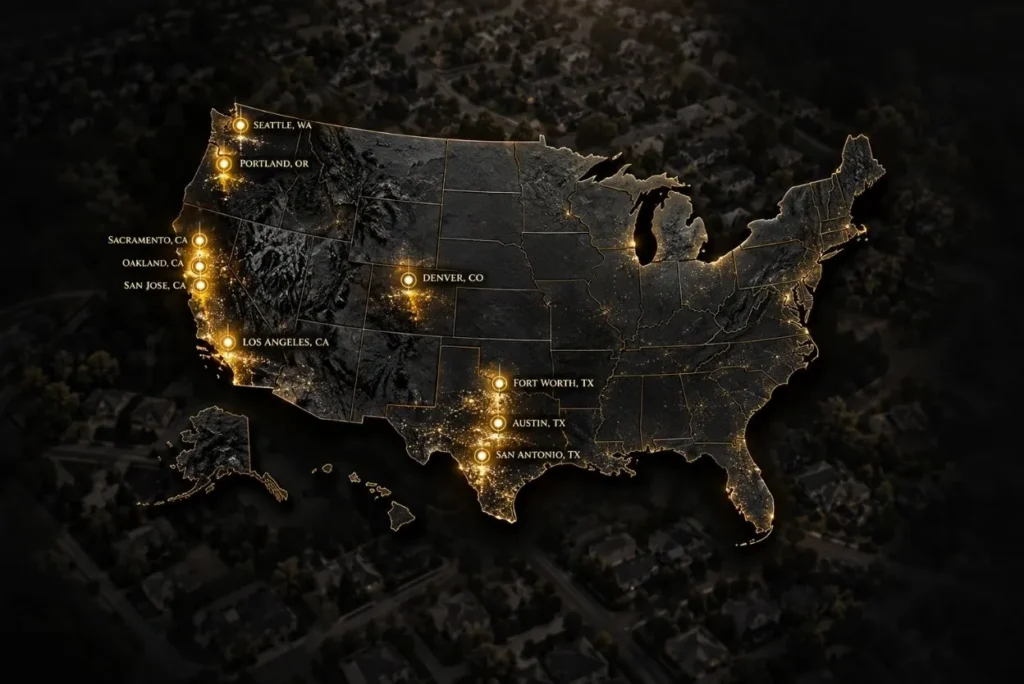
Here are the 10 metros closest to normal, with each one’s current year-over-year price growth and projected annual income growth:
- San Jose, CA: -3.2% prices, 6.5% income growth
- Austin, TX: -2.9% prices, 4.9% income growth
- Oakland, CA: -0.3% prices, 6.5% income growth
- Seattle, WA: -2.9% prices, 5.8% income growth
- Portland, OR: -0.1% prices, 5.6% income growth
- San Antonio, TX: -0.8% prices, 3.2% income growth
- Sacramento, CA: 0% prices, 4.9% income growth
- Denver, CO: 0.7% prices, 4.9% income growth
- Los Angeles, CA: 0.7% prices, 4.9% income growth
- Fort Worth, TX: -0.9% prices, 3.5% income growth
Normal doesn’t mean affordable in several of these markets. Locals in San Jose, Oakland and Seattle, and in Portland to a lesser extent, tend to earn more than the average American, but homes there are pricey enough to stay out of reach for a lot of residents.
Half the Metros Could Wait 10+ Years
In half the metros Redfin studied, costs could take at least 10 years to return to normal at any mortgage rate between 6% and 8%. Many of these markets are in the Northeast and Midwest, and plenty of them have home prices growing faster than the national average.
Chicago and Nassau County, NY (Long Island) are good examples. In both metros, home prices are rising faster than incomes:
- Chicago: prices up 5.5% year over year, with projected income growth of 3.9%
- Nassau County: prices up 5.3% year over year, with projected income growth of 3.6%
Redfin says these markets tend to be more competitive than the West Coast or the Sun Belt. Nassau County is the strongest seller’s market in the country, and Chicago is hotter than most other U.S. metros.
Redfin Senior Economist Asad Khan explained why the country’s priciest markets could return to normal before places like Chicago.
“It may seem counterintuitive that housing costs could return to normal sooner in the country’s most expensive markets than in a place like Chicago or Philly, but it comes down to the direction of home prices and incomes. In parts of the West, home prices are falling while we expect incomes to keep rising, gradually bringing the markets back to a baseline. But in many Midwest and East Coast markets, home prices are still climbing faster than incomes—so, even if rates were to drop meaningfully, a buyer’s monthly payment wouldn’t return to something that feels normal anytime soon.”
Here are all 24 metros where costs could take at least a decade to return to normal if rates stay between 6% and 8% and prices keep growing at their current pace:
- Anaheim, CA
- Baltimore, MD
- Chicago, IL
- Cincinnati, OH
- Cleveland, OH
- Columbus, OH
- Detroit, MI
- Fort Lauderdale, FL
- Indianapolis, IN
- Jacksonville, FL
- Kansas City, MO
- Milwaukee, WI
- Montgomery County, PA
- Nassau County, NY
- New Brunswick, NJ
- Newark, NJ
- New York, NY
- Philadelphia, PA
- Providence, RI
- St. Louis, MO
- Tampa, FL
- Virginia Beach, VA
- Warren, MI
- West Palm Beach, FL
The Play for Agents
Khan had this advice for buyers who feel stuck between buying at today’s rates and waiting.
“Many house hunters feel stuck between two bad options: Stretch themselves to buy at today’s rates, or wait for lower rates only to see prices climb further out of reach. But prospective buyers shouldn’t get hung up on timing the market. These hypothetical scenarios should give would-be buyers and sellers some hope that the market can normalize with only modest changes in rates or prices.
“For buyers and sellers, that means the best time to make a move is when it makes sense for your finances and your life. If you’re a buyer who needs more time to save for a down payment, take more time. If you’re a buyer who has the means to buy at current costs and you find your dream home, don’t let today’s rates stop you.”
Redfin’s metro timelines give agents something concrete to bring to your conversations with buyers longing for a return to “normal” affordability levels.
Defining terms is a good first step. Redfin defines “normal” as a return to 2018 levels (relative to household income), which isn’t the same thing as affordable.
So, if you’re talking to buyers frustrated by the higher list prices for homes in their area, start by getting clarity on the real need behind the question, “Will the housing market ever be normal again?”
Start with this:
“Redfin just put out a report on exactly that. Best case, we’re talking two to three years. Worst case, ten or more. And that’s just for monthly payment-to-income ratios to feel like 2018 again, not for prices to drop. So I want to ask you something: what does ‘normal’ actually look like for you?”
If they push back with something like, “I just think prices will come down,” here’s what you can say to give them a clearer idea of what to expect, based on the data:
“Can I share what the data shows?
(Pause for an answer.)
“In most markets, prices aren’t falling. They’re still climbing. The metros where costs are normalizing fastest are the ones where prices dropped AND incomes grew. In most of the country, that’s not happening. So the question isn’t whether normal is coming. It’s whether waiting gets you there faster or just costs you more.”
Next up, you lay out the two options they’re facing:
“Here’s what I want to walk you through. Path A: you buy now, you lock in today’s price, at a monthly payment you can afford. Path B: you wait, rates maybe drop a little, but prices in this market are up five percent year over year. Which path puts more money in your pocket?”
The 5% is hypothetical. If you have a more accurate percentage for home price increases for your market, one or more years out (depending on how long they’re talking about waiting), use that instead.
And for the closing:
“I’m going to pull the numbers specific to [Your City/Neighborhood] and send them over today. Then let’s get 15 minutes on the calendar to walk through what it actually means for you here. I have Thursday at 2 pm or Friday at 10 am. Which works better?”
All the above scripts come from the BAMx Script Advisor, which is built on the BAMx live Roleplay Mastermind with Byron Lazine, Lisa Chinatti, and Tom Toole.
Sign up for a free trial to get full access.